A single hairline scratch on a McLaren Artura or a minor scuff on a Porsche 911 GT3 RS can quickly evolve into a five-figure financial headache. When you’re behind the wheel of a high-performance machine, standard coverage often leaves a massive gap between a thrilling drive and a costly mistake. You might be asking yourself: should I get extra insurance for a supercar rental? It’s natural to feel a bit of tension regarding the complex terminology of Excess and CDW while planning your elite travel.
You want the prestige of a Ferrari without the looming fear of massive out-of-pocket expenses for minor incidents. This guide is designed to provide total clarity on your financial exposure. You’ll discover the critical differences between mandatory third-party liability and premium waivers that protect your capital. We’ll explore how Super CDW options eliminate repair costs and explain the essential steps for handling incidents in the UAE. By the end, you’ll have the knowledge to secure a seamless, worry-free rental experience that prioritizes your peace of mind and keeps your focus on the road ahead.
Key Takeaways
- Understand why mandatory Third-Party Liability is the legal baseline in the UAE but leaves your high-performance vehicle unprotected in an at-fault incident.
- Analyze the specific financial thresholds of standard excess to determine should I get extra insurance for a supercar rental to protect your liquidity.
- Compare Collision Damage Waiver (CDW) and Super CDW to learn how to achieve “Zero Excess” status and effectively eliminate out-of-pocket repair costs.
- Identify critical contract clauses like “Loss of Use” liability that can significantly impact your total financial exposure beyond simple repair bills.
- Discover how transparent, no-deposit rental models from trusted providers like Delta Rentals remove traditional industry friction for a seamless experience.
Understanding Standard Supercar Rental Insurance in the UAE
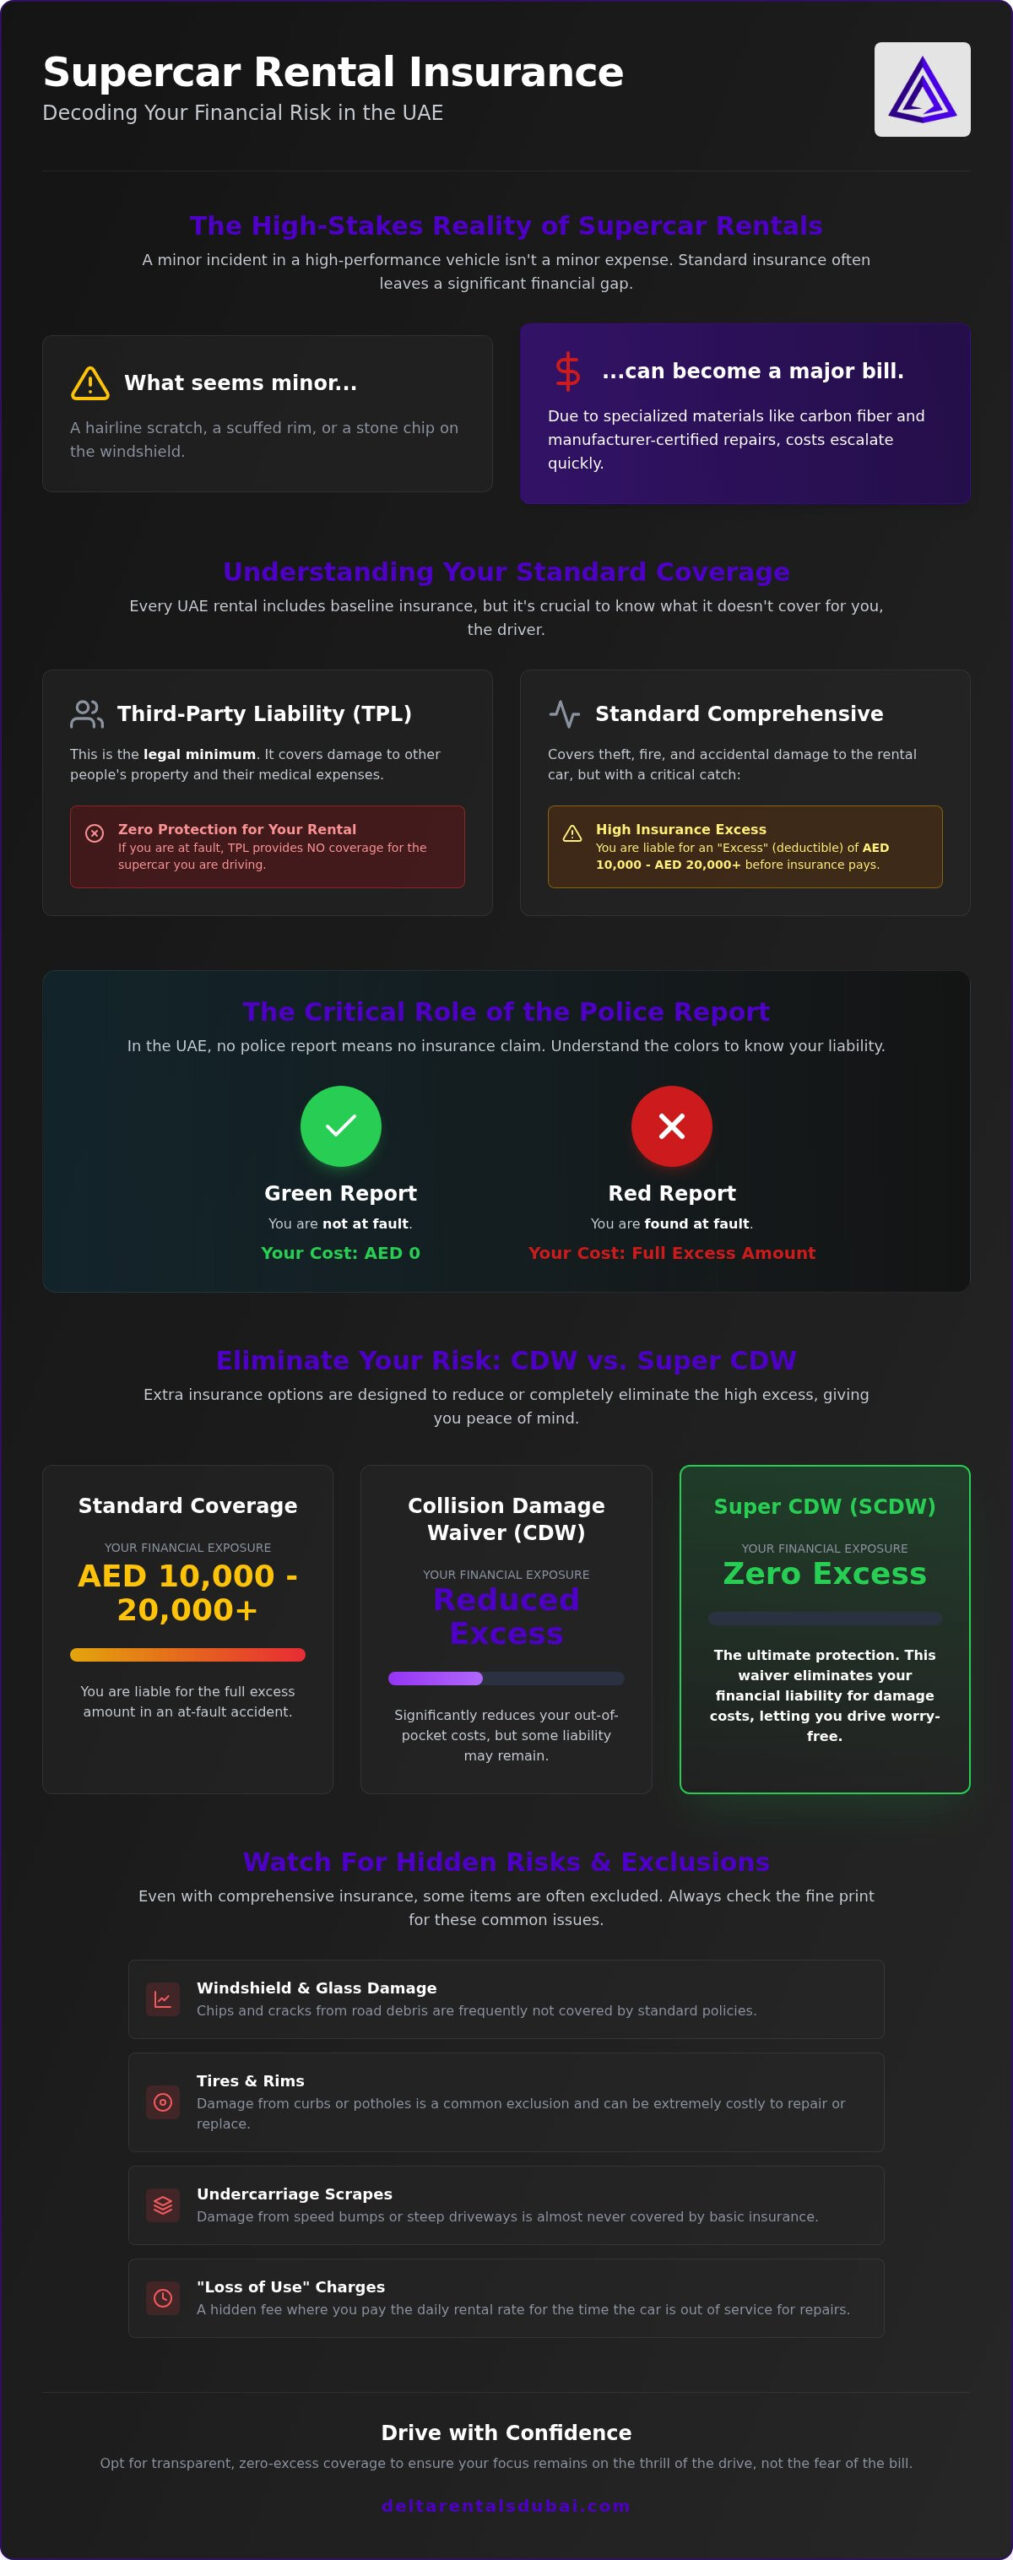
Every supercar rental in the UAE begins with a legal baseline called Third-Party Liability (TPL). This is non-negotiable and mandatory by law. It ensures that if an accident occurs, the medical expenses and property damage of other people involved are covered. However, TPL offers zero protection for the high-value asset you’re driving. If you rely solely on this legal minimum, you’re personally liable for every dirham of damage to the vehicle itself.
Most reputable providers upgrade this baseline to Comprehensive Insurance. This typically covers fire, theft, and accidental damage to the rental car. But there’s a significant catch: standard comprehensive insurance is designed to protect the rental company’s asset, not your liquidity. It always includes an “Excess” or deductible. For elite vehicles, this out-of-pocket limit can range from AED 10,000 to AED 20,000 or more. This substantial financial exposure is the primary reason many drivers ask: should I get extra insurance for a supercar rental?
The Legal Minimum vs. Comprehensive Protection
Standard comprehensive packages for a Porsche 911 GT3 RS or similar high-performance models often come with strict boundaries. While the car’s main bodywork is covered, specific high-wear areas are frequently excluded from standard agreements. You’ll often find yourself responsible for:
- Windshield chips and cracks from road debris
- Rim scuffs and tire damage from curbs
- Undercarriage scrapes from speed bumps
Without a Collision Damage Waiver (CDW) or a more robust upgrade, these “minor” issues become your full financial responsibility. Standard coverage protects the rental fleet’s value; it doesn’t protect you from the high costs of supercar parts and specialized labor.
The Role of the Police Report in UAE Insurance
In the UAE, insurance claims are strictly invalid without an official police report. This is a hard rule that applies to every driver on the road. If you return a car with “unknown damage” found after parking, you’ll likely be charged the full repair cost. No report means no insurance activation. Understand the color coding of these reports to gauge your liability:
- Green Report: You’re not at fault. You typically pay nothing.
- Red Report: You’re found at fault. You must pay the insurance excess.
Even with a premium policy, a Red Report triggers that pre-agreed excess amount. Navigating these rules requires a partner who explains these details before you turn the key. High-performance driving demands high-performance protection that goes beyond the bare legal minimum.
The Financial Risks of Standard Coverage: Why Basic Isn’t Enough
Driving a vehicle worth over 1,000,000 AED changes the math of a “minor” incident. For a standard sedan, a door ding is a nuisance; for a supercar, it’s a structural and aesthetic crisis. Standard coverage often leaves you vulnerable to the “Supercar Premium,” where specialized components carry costs that far exceed typical insurance limits. When considering consumer advice on rental insurance, it’s clear that high-value assets require a more tactical approach to protect your personal capital. You don’t want your travel budget evaporated by a single piece of road debris.
The Excess is your primary point of exposure. In the UAE, the insurance excess for sports and exotic cars often ranges between AED 10,000 and AED 20,000. This is the amount you must pay out-of-pocket before the insurance company contributes a single fil. If you’re wondering, “should I get extra insurance for a supercar rental,” the answer lies in whether you’re comfortable with a sudden, five-figure deduction from your liquidity. Relying on basic plans means your security deposit is effectively on the line for every kilometer you drive.
The Reality of Supercar Repair Costs
Modern supercars utilize advanced materials like carbon fiber and multi-stage pearlescent paints. These cannot be “patched” at a local shop. Maintaining manufacturer warranties requires genuine OEM parts and certified technicians, which drives labor costs into a different tier. A single carbon fiber splitter can cost more than a standard car’s entire engine. In the UAE, the average insurance excess for a supercar is typically around AED 10,000.
Loss of Use Charges: The Hidden Rental Risk
One of the most overlooked risks is “Loss of Use.” If a Ferrari is in the workshop for two weeks awaiting parts from Italy, the rental company loses two weeks of potential revenue. Standard insurance rarely covers this deficit. You might find yourself billed for the daily rental rate of a car you aren’t even driving. Extra insurance options often waive or cap these secondary costs, ensuring a minor mishap doesn’t turn into a month-long financial drain. If you value transparency, you can speak with our experts about tailored coverage for your next drive. We believe in removing the friction from your luxury experience.
Comparing Extra Insurance Options: CDW vs. Super CDW
Choosing the right protection level transforms your driving experience from a high-stakes gamble into pure, unadulterated performance. While the legal baseline covers others, extra insurance options like the Collision Damage Waiver (CDW) and Super CDW are designed to protect you. These aren’t technically insurance policies but legal waivers where the rental company agrees to forgo their right to collect high damages from you. If you’re debating “should I get extra insurance for a supercar rental,” consider the psychological freedom of knowing a minor error won’t derail your financial week.
Standard CDW acts as a financial ceiling. It caps your liability at the “Excess” amount discussed in previous sections, ensuring you aren’t liable for the full market value of the vehicle. Super CDW, often called Full Coverage or Zero Excess, takes this a step further by reducing that liability to zero. For many, the modest daily cost of a Super CDW is a small price for “Zero Excess” status. Additionally, Personal Accident Insurance (PAI) provides a vital safety net for the driver and passengers, covering medical expenses or accidental disability, which standard vehicle waivers often omit.
CDW vs. Super CDW: A Side-by-Side Analysis
The choice often depends on the specific vehicle and your personal risk tolerance. Consider a Rolls Royce Cullinan. A standard CDW might still leave you responsible for a 10,000 AED excess in the event of an at-fault accident. While this is better than paying for a 2,000,000 AED vehicle, it’s still a significant hit. Experienced drivers who are intimately familiar with UAE traffic might find a standard CDW sufficient. However, most elite travelers prefer the Super CDW to achieve total peace of mind, ensuring that even a “Red Report” from the police results in zero out-of-pocket repair costs.
Exclusions Even in “Full Coverage” Policies
Even the most comprehensive “Full Coverage” packages have hard boundaries you must respect. Understanding these exclusions is the hallmark of a savvy renter. Standard and extra waivers are almost universally voided by the following:
- Off-Road Use: Taking a supercar onto sand dunes or unpaved tracks voids all insurance immediately.
- Reckless Conduct: Driving under the influence or participating in illegal street racing cancels your protection.
- Tyre and Rim Damage: This is the most common “extra” not covered by standard CDW. Rims on a Ferrari or Lamborghini are precision-engineered and incredibly expensive to replace if curbed.
Always verify if your “Zero Excess” policy includes glass and tire protection. These are high-frequency damage items that can still trigger costs if not explicitly included in your premium waiver. Directness and clarity in your rental agreement are your best tools for a frictionless experience.
A 5-Point Checklist for Evaluating Supercar Insurance
Before you sign the agreement and take the keys, a systematic review of your coverage is essential. High-performance rentals operate under different financial rules than standard vehicles. If you’re still debating should I get extra insurance for a supercar rental, use this 5-point checklist to expose any hidden vulnerabilities in your contract. Clarity now prevents a financial crisis later.
- Verify the exact Excess: Don’t rely on verbal estimates. Ensure the specific AED amount for which you’re liable is clearly stated in the written agreement.
- Check for “Loss of Use” clauses: Confirm if you’re responsible for the daily rental revenue lost while the car is undergoing repairs. These costs can easily double your repair bill.
- Confirm tyre and windshield protection: These are high-frequency damage items often excluded from standard CDW packages. Ask if they are included in your premium waiver.
- Review personal insurance exclusions: Check if your domestic policy or travel insurance specifically excludes “exotic” or “high-value” vehicles. Most do.
- Explain the police report process: Ask the rental desk exactly how to obtain a report and what documentation they require to process a claim. You need this information before an incident occurs.
The Credit Card Insurance Trap
Many elite travelers assume their premium credit card provides sufficient coverage. This is a dangerous misconception in the luxury automotive sector. Most premium cards explicitly exclude vehicles with an MSRP over $100,000. Considering a McLaren Artura or Ferrari F8 costs significantly more, your card’s protection is likely void the moment you start the engine. Even if your card claims to cover international rentals, the burden of proof is high. You’ll often have to pay the full repair costs out-of-pocket in the UAE and spend months attempting to claim the funds back from your bank. It’s a liquidity drain that most high-net-worth individuals prefer to avoid.
Documenting the Vehicle State
Precision documentation is your best defense against “Unknown Damage” claims. Conduct a thorough pre-rental walk-around video in high resolution. Focus specifically on the rims, as curb rash is the most common point of contention. Inspect the underbody and front splitter for existing scrapes from speed bumps. Ensure every minor blemish is noted on the insurance-signed document before you depart. This level of transparency protects both parties and ensures a seamless return process. If you want a rental partner that prioritizes this level of honesty, connect with our team for a transparent booking experience today. We believe in removing every barrier to your prestige experience.
Experience Seamless Prestige: The Delta Rentals Distinction
Choosing a high-performance vehicle should be an exercise in pure adrenaline, not financial anxiety. While other providers might leave you wondering, “should I get extra insurance for a supercar rental,” Delta Rentals Dubai removes the guesswork through radical transparency. We don’t just provide a fleet; we provide a “no-scam” philosophy that prioritizes your peace of mind from the moment you inquire until the keys are returned. Every policy detail is explained upfront, ensuring you never encounter a hidden fee or an unexpected insurance clause.
Our “No Deposit” advantage serves as a cornerstone of this trust. While the industry standard involves blocking significant sums on your credit card for weeks, we’ve streamlined the process to emphasize effortless prestige. This model reflects our confidence in our clientele and our commitment to a frictionless experience. Whether you are behind the wheel of a Ferrari or one of our Luxury SUVs, your liquidity remains protected. You get the status you deserve without the traditional industry friction.
Why Transparency is Our Primary Service
In a market where vague terms and hidden deductibles are common, we stand as the most transparent car rental company in the UAE. We’ve built our reputation by being the honest partner that explains the nuances of Excess and CDW before you sign anything. Our 300+ 5-star Google reviews reflect this dedication to integrity. You have direct access to management for any complex insurance queries, ensuring that your protection strategy is as tailored as your driving route. We believe that an empowered client is a satisfied client.
Booking Your Protected Experience
Securing your next high-status experience is as simple as a conversation. Our WhatsApp-based booking system allows for rapid verification and clear communication regarding your coverage options. If you are looking to add extra protection to your Porsche or McLaren hire, our concierge team can facilitate that upgrade instantly. We handle the technicalities so you can focus on the performance. Don’t settle for “standard” when you can have elite protection and total clarity. Book your next supercar experience with Delta Rentals Dubai and discover the difference that honesty makes.
Secure Your High-Performance Journey
Driving an elite vehicle should be an experience of pure freedom, not a calculation of potential liability. You’ve learned that standard UAE coverage often leaves your personal capital exposed to high excess fees and hidden “Loss of Use” charges. When deciding should I get extra insurance for a supercar rental, the answer usually lies in your desire for “Zero Excess” peace of mind. By choosing the right waiver, you ensure that a minor incident never compromises your travel budget or your focus on the road.
Delta Rentals Dubai stands as the most transparent car rental company in the UAE, backed by 300+ 5-star Google reviews. We remove the traditional friction of luxury rentals by offering no-deposit options for elite clients and clear, upfront terms. Our team acts as your high-status partner, providing the expert guidance you need to drive with total confidence. Don’t let insurance complexity stand between you and the engine’s roar. It’s time to transition into a seamless, high-status experience where your protection is as refined as the car you drive.
Rent with Confidence at Delta Rentals Dubai
Frequently Asked Questions
Is insurance mandatory for renting a supercar in the UAE?
Yes, basic Third-Party Liability (TPL) insurance is legally required for every rental vehicle in the UAE. This mandatory coverage protects you against financial claims from third parties for injuries or property damage. However, it doesn’t cover the high-performance car you’re driving. To protect the asset and your own wallet, you must consider whether the standard comprehensive plan is enough or if you require a more robust waiver for total security.
What is the difference between CDW and full insurance for exotics?
A Collision Damage Waiver (CDW) limits your financial responsibility to a pre-agreed excess amount if the car is damaged. Full insurance, often called Super CDW, aims to eliminate this out-of-pocket expense entirely. While standard CDW still leaves you liable for thousands, full coverage provides a “Zero Excess” experience. This distinction is vital when asking should I get extra insurance for a supercar rental to ensure your liquidity remains untouched.
Does my credit card insurance cover a Porsche 911 GT3 RS?
Unlikely. Most premium credit cards explicitly exclude “exotic” vehicles or those with a high manufacturer’s suggested retail price from their rental insurance benefits. A Porsche 911 GT3 RS far exceeds the typical value thresholds set by major banks. Relying on a personal card often results in a denied claim or requires you to pay the full repair costs upfront. Always verify your specific card’s exclusions before assuming you’re protected for high-value assets.
What happens if I have an accident in a rental supercar?
You must immediately secure the scene and contact the local police to obtain an official report. Even for minor scratches, a police report is the only way to activate your insurance coverage. Once you have the report, notify the rental company’s concierge team to handle the vehicle recovery or replacement. Following this strict legal protocol is the only way to limit your liability to the agreed excess amount or zero.
Can I get a supercar rental with no deposit and full insurance?
Yes, Delta Rentals specializes in no-deposit supercar rentals, allowing you to pair elite vehicles with full insurance for a seamless experience. This trust-based model removes the need for large credit card blocks, providing you with immediate access to our fleet. By combining a no-deposit agreement with a Super CDW, you achieve the highest level of financial protection and convenience available in the luxury rental market today.
Are tyre and rim damages covered by standard supercar insurance?
Standard supercar insurance policies almost always exclude damage to tyres, rims, and glass. These are considered high-wear items and are the most common points of damage in high-performance driving. If you curb a rim or catch a stone chip on the windshield, you’ll be responsible for the full OEM replacement cost. We recommend checking if your premium waiver specifically includes these items to avoid unexpected bills upon vehicle return.
Why do I need a police report for insurance claims in the UAE?
A police report is a mandatory legal requirement for any insurance claim to be processed in the UAE. Without this official document, the insurance provider cannot verify the circumstances of the incident, making the driver personally liable for all damages. This rule applies regardless of who was at fault. Obtaining the report ensures a transparent claims process and is the primary factor in determining if you pay the excess or nothing.
Does extra insurance cover off-road driving in the desert?
No insurance policy, including premium extra coverage, provides protection for off-road driving in the desert. Supercars are engineered for high-speed asphalt performance, and taking them onto sand dunes or unpaved tracks violates the rental agreement. Such actions void all insurance immediately, leaving the driver liable for the full value of the vehicle. Please note that Delta Rentals does not offer or permit off-road desert safari tours with our fleet.